Component-level accruals
See the calculation supporting each Major Capital Item total.
A Body Corporate’s Reserve Fund is more than a balance in the bank. To understand its funding position, it must be considered against the maintenance, repair and replacement obligations recorded in its 10-year MRR Plan.
Without the underlying plan, that analysis cannot be performed accurately.
OBC turns the Body Corporate’s Component-level MRR information into clear, ready-to-use schedules for its Accountant and Auditor.
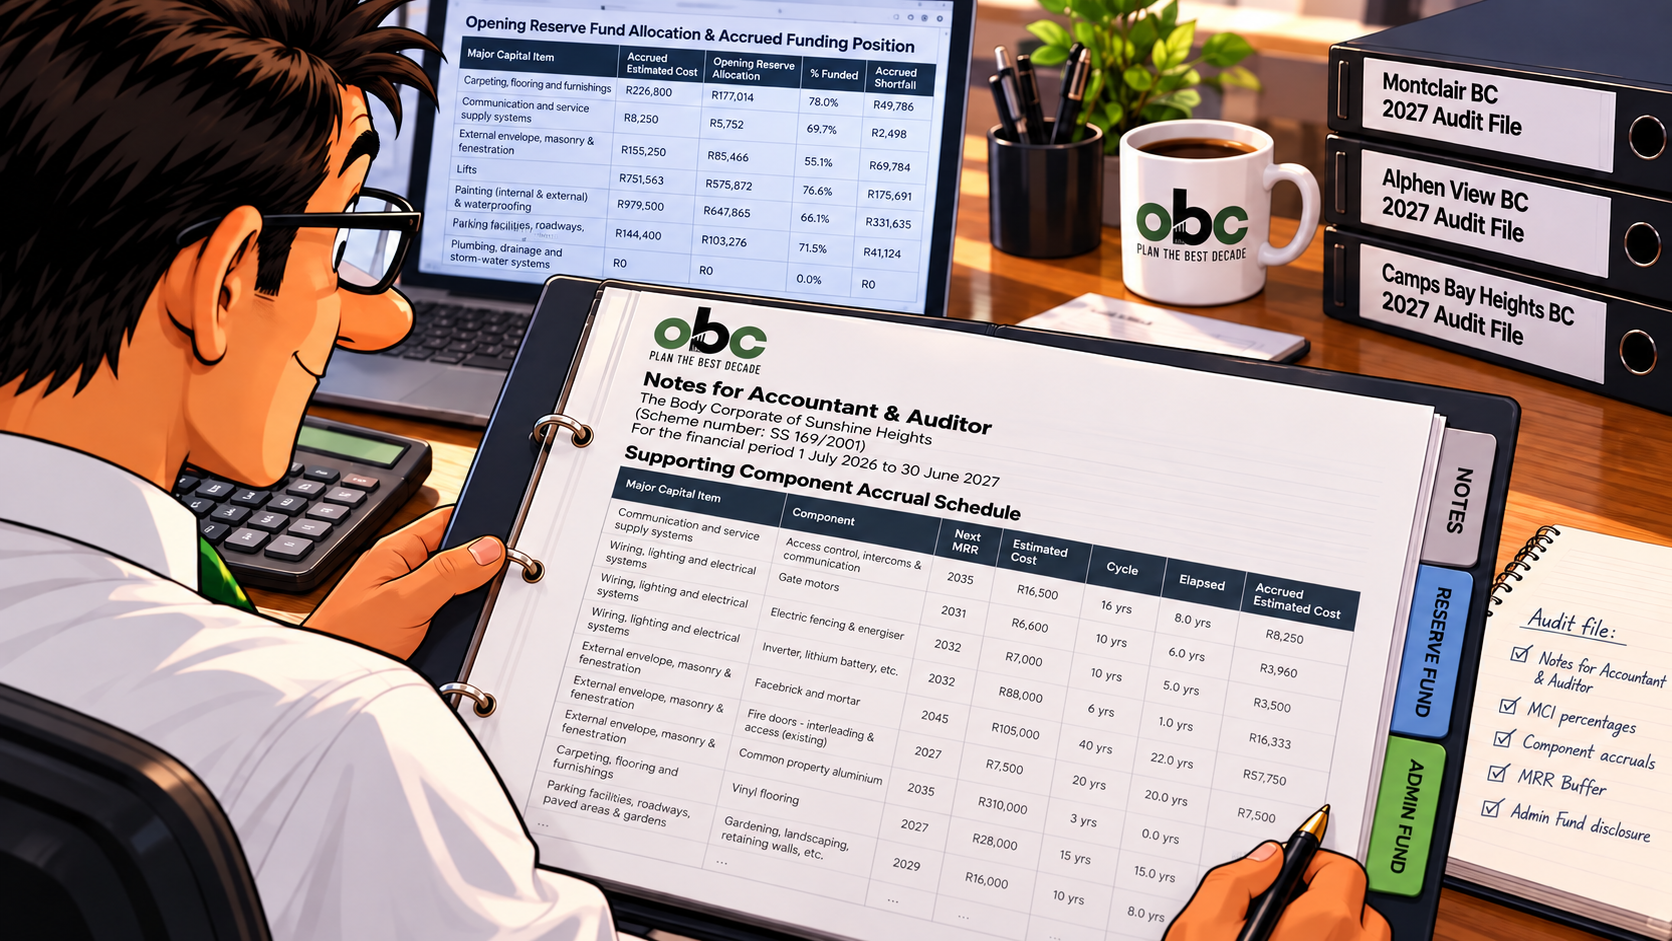
OBC calculates accrued estimated cost at Component level using the elapsed proportion of each Component’s current maintenance cycle, then aggregates those amounts by Major Capital Item. The opening Reserve Fund balance is allocated across those accrued requirements, with the MRR Buffer shown separately.
Accountant information: PMR 26 requires the annual financial statements to analyse the amount available for each Major Capital Item as a percentage of its accrued estimated cost and to show any rand shortfall.
| Major Capital Item | Accrued Estimated Cost | Opening Reserve Allocation | % Funded | Accrued Shortfall |
|---|---|---|---|---|
| Carpeting, flooring and furnishings | R226,800 | R177,014 | 78.0% | R49,786 |
| Communication and service supply systems | R8,250 | R5,752 | 69.7% | R2,498 |
| External envelope, masonry & fenestration | R155,250 | R85,466 | 55.1% | R69,784 |
| Lifts | R751,563 | R575,872 | 76.6% | R175,691 |
| Painting (internal & external) & waterproofing | R979,500 | R647,865 | 66.1% | R331,635 |
| Parking facilities, roadways, paved areas & gardens | R144,400 | R103,276 | 71.5% | R41,124 |
| Plumbing, drainage and storm-water systems | R0 | R0 | 0.0% | R0 |
| Security systems and facilities | R0 | R0 | 0.0% | R0 |
| Wiring, lighting and electrical systems | R59,543 | R30,760 | 51.7% | R28,784 |
| MCI TOTAL | R2,325,306 | R1,626,005 | 69.9% | R699,301 |
| MRR Buffer — PMR 24(3)(d) | R30,650 | R20,360 | 66.4% | R10,290 |
| TOTAL RESERVE FUND | R2,355,956 | R1,646,365 | 69.9% | R709,591 |
MRR Buffer — PMR 24(3)(d) is calculated separately from qualifying uncompleted current-financial-year and next-financial-year Component expenditure under the selected OBC Buffer policy. It is not a Major Capital Item and is shown separately from the PMR 26 MCI percentages.
Every Major Capital Item total can be traced back to the Components in the plan: the next MRR year, estimated cost, maintenance cycle, elapsed period and resulting accrued estimated cost.
| Major Capital Item | Component | Next MRR | Estimated Cost | Cycle | Elapsed | Accrued Estimated Cost |
|---|---|---|---|---|---|---|
| Communication and service supply systems | Access control, intercoms & communication | 2035 | R16,500 | 16 yrs | 8.0 yrs | R8,250 |
| Wiring, lighting and electrical systems | Gate motors | 2031 | R6,600 | 10 yrs | 6.0 yrs | R3,960 |
| Wiring, lighting and electrical systems | Electric fencing & energiser | 2032 | R7,000 | 10 yrs | 5.0 yrs | R3,500 |
| Wiring, lighting and electrical systems | Inverter, lithium battery, etc. | 2032 | R98,000 | 6 yrs | 1.0 yrs | R16,333 |
| External envelope, masonry & fenestration | Facebrick and mortar | 2045 | R105,000 | 40 yrs | 22.0 yrs | R57,750 |
| External envelope, masonry & fenestration | Fire doors - interleading & escape (existing) | 2027 | R7,500 | 20 yrs | 20.0 yrs | R7,500 |
| External envelope, masonry & fenestration | CP & share of section aluminium, steelwork, woodwork, etc. | 2027 | R90,000 | 2 yrs | 2.0 yrs | R90,000 |
| External envelope, masonry & fenestration | Common property aluminium | 2035 | R310,000 | 3 yrs | 0.0 yrs | R0 |
| Carpeting, flooring and furnishings | Vinyl flooring | 2027 | R28,000 | 15 yrs | 15.0 yrs | R28,000 |
| Parking facilities, roadways, paved areas & gardens | Gardening, landscaping, retaining walls, etc. | 2029 | R18,000 | 10 yrs | 8.0 yrs | R14,400 |
| Wiring, lighting and electrical systems | Borehole pumps, water pumps, pool pumps, irrigation, etc. | 2028 | R39,000 | 12 yrs | 11.0 yrs | R35,750 |
| Painting (internal & external) & waterproofing | Redecoration (vertical walls, soffits, horizontal surfaces) | 2029 | R1,200,000 | 8 yrs | 6.0 yrs | R900,000 |
| Carpeting, flooring and furnishings | Terrazzo tiles | 2031 | R210,000 | 75 yrs | 71.0 yrs | R198,800 |
| Parking facilities, roadways, paved areas & gardens | Asphalt (tar), including parking lines & markings | 2027 | R130,000 | 10 yrs | 10.0 yrs | R130,000 |
| Plumbing, drainage and storm-water systems | Downspout, gutters, pipes, reticulation, valves, etc. | 2037 | R50,000 | 10 yrs | 0.0 yrs | R0 |
| Security systems and facilities | CCTV Camera System | 2036 | R18,000 | 6 yrs | 0.0 yrs | R0 |
| Lifts | Machine-room-less elevator | 2033 | R925,000 | 32 yrs | 26.0 yrs | R751,563 |
| Painting (internal & external) & waterproofing | Waterproofing torch-on membrane | 2028 | R12,000 | 2 yrs | 1.0 yrs | R6,000 |
| Painting (internal & external) & waterproofing | Polyurethane Roof Coating | 2030 | R105,000 | 10 yrs | 7.0 yrs | R73,500 |
See the calculation supporting each Major Capital Item total.
See the percentage funded and any accrued shortfall.
Keep the additional Reserve Fund amount distinct from MCI allocations.
If a Body Corporate you audit or prepare accounts for does not yet have its 10-year MRR Plan on OBC, invite the Trustees or Community Scheme Manager to prepare it before the annual financial statements are finalised.
The 10-Year MRR Plan shouldn’t be a document produced once for a clean audit. It is a living plan — connected to the Reserve Fund, contributions, maintenance expenditure and the decisions behind them.
Keeping the MRRP electronic makes communication between accountants and auditors easier. The same plan, schedules and supporting information remain available as Trustees, Community Scheme Managers and accounting professionals change.
PLAN IT. FUND IT. MAINTAIN IT. RECORD IT.